Institutional decision architecture · Backtesting based

Disciplined data intelligence for digital portfolios instead of gut feeling

Zarvenor analyzes large amounts of market data in real time, checks every allocation logic in historical market regimes and supports you with comprehensible recommendations for risk control and allocation discipline.

Note: Zarvenor is a software platform for data-driven decision support. Historical backtest results are not an indicator or guarantee of future returns. Digital assets involve significant risks of loss.

Analytical context

Volatility requires systematicity, not emotion

Digital asset markets react quickly to liquidity changes, narrative changes and structural breaks. For many investors, this creates a decision-making problem: signals are numerous, but their reliability remains unclear.

Zarvenor addresses this uncertainty with a testable decision architecture. Each recommendation is derived from real-time data and previously tested against historical volatility clusters and periods of stress.

Check decision logic
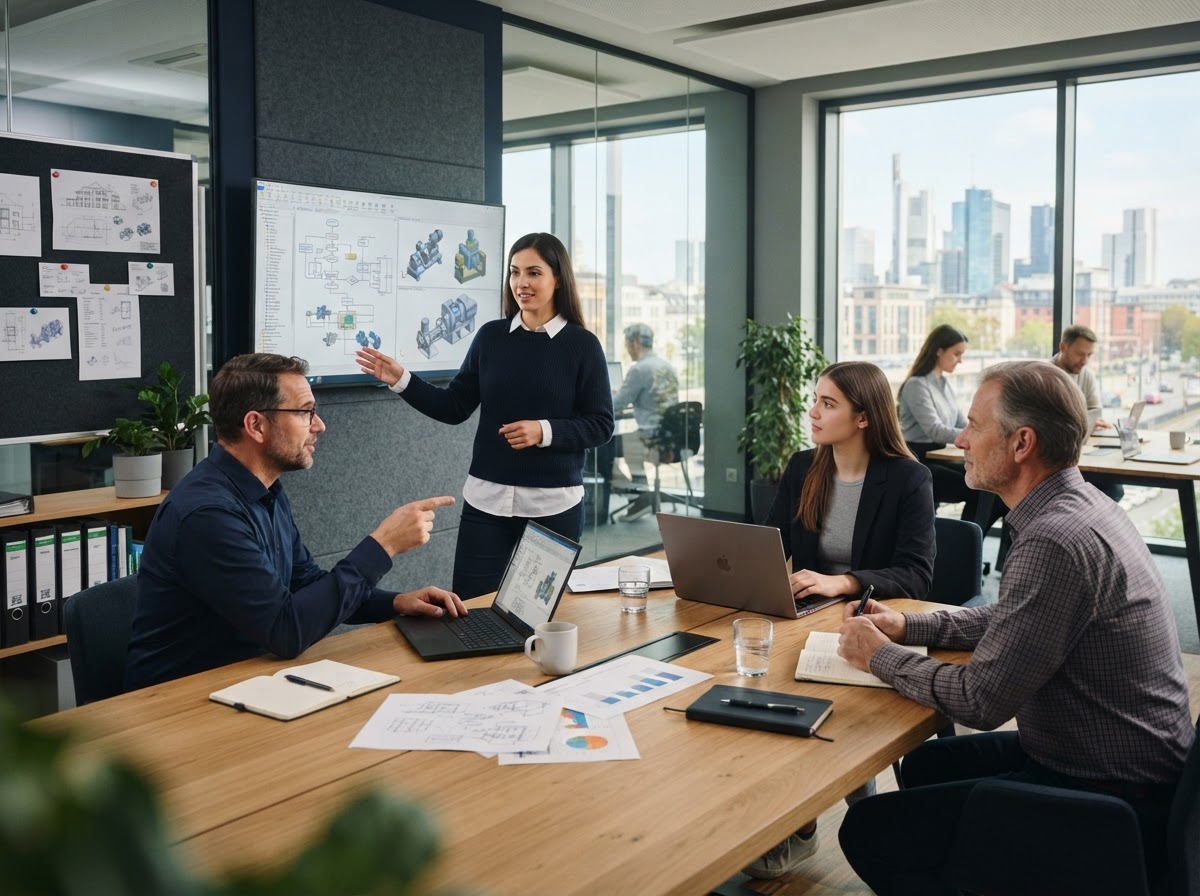
Zarvenor team analyzing market regimes and risk models

Structured analysis instead of forecast promises: market regime recognition, liquidity metrics and documented model assumptions.

criterionEmotion-driven approachZarvenor decision architecture
Data basisIndividual news and price movementsAggregated order book, volatility and liquidity data with timestamp
ValidationRetrospective justification of individual tradesOut-of-sample backtesting and walk-forward analysis before every release
Risk managementReactive adjustment after lossesPre-defined downside thresholds and drawdown limit
TraceabilityDifficult to documentTransparent audit trails for every model recommendation

Backtesting methodology

First the stress test, then the recommendation

Our process ensures that no allocation recommendation is made without historical review. We simulate how a rule would have reacted in different market regimes and only then calibrate the risk and weighting.

Step 01

Real-time data aggregation

Prices, volatility, liquidity and market structure are continuously merged, adjusted and versioned.

Step 02

Historical regime simulation

Rules go through bull, sideways and correction phases, including liquidity bottlenecks and structural breaks.

Step 03

Risk and drawdown calibration

Volatility clusters and confidence intervals determine thresholds for weighting and capital preservation.

Step 04

Allocation recommendation

Only after passing the test will you receive a weighted, justified and documented recommendation.

Technical note on out-of-sample testing: Training and testing periods are strictly separated. Parameters are developed on a data set and validated on an unseen time period to limit overfitting. Walk-forward windows also check stability over time.

Decision-making skills

Tools for allocation discipline in everyday life

The platform supports private investors, family offices and treasury managers with clearly defined functions. No automatic asset management, but a reliable basis for decision-making.

1. Predictive volatility modeling

Early detection of regime changes based on volatility, market breadth and liquidity.

  • Market regime detection with confidence assessment
  • Transparent model assumptions and boundaries

2. Automated rebalancing signals

Rule-based advice for weight adjustment when thresholds are systematically violated.

  • Comprehensible triggers instead of discretionary interventions
  • Matching your risk profile

3. Downside protection thresholds

Pre-defined limits on drawdowns and position sizes to support capital preservation.

  • Clear escalation logic in times of stress
  • Documentation of each threshold adjustment

4. Audit trail for each output

Each recommendation contains data status, backtest reference and applied rules.

  • Exportable minutes for internal committees
  • Suitable for B2B testing processes

Scenario simulation

How the decision logic works in three market phases

The following regimes describe how the model works. These are methodological explanations, not earnings forecasts or customer cases.

Regime A: Market structure break and capital preservation

Detection: volatility jumpResponse: Reduce weightingGoal: Limit drawdown

In the event of sudden structural breaks, the model prioritizes capital preservation. If the realized volatility rises above the calibrated threshold and the order book depth deteriorates, a reduction in exposure is recommended. The decision remains documented in the audit trail with a timestamp and threshold.

Regime B: Trend confirmation and weight adjustment

Detection: stable market breadthResponse: gradual allocationGoal: Maintain discipline

In stable upward phases with confirmed market breadth, the system suggests a gradual adjustment of the weighting. Increases occur in defined stages and only within the previously defined risk budgets in order to avoid pro-cyclical overweighting.

Regime C: Liquidity shortage and early warning

Detection: Spread wideningResponse: Warning level + hedging optionGoal: To ensure the ability to act

If liquidity and trading volumes narrow, the model generates an early warning with a classification of the consequences. Investors are given concrete options for action, such as reducing positions or waiting until things normalize, including documented data.

Transparency note on methodology: The processes shown illustrate decision-making rules. They do not represent a guarantee of specific results. Historical patterns do not necessarily repeat themselves; confidence intervals describe uncertainty, not certainty.

Investor FAQ

Answers for risk-conscious investors

How does backtesting prevent overfitting?

Training and test data are strictly separated. Strategy logics are developed over time and tested on unseen out-of-sample data. Additionally, we use walk-forward analyzes with rolling windows. Rules that only work in a single time period will not be released.

Does Zarvenor hold my assets?

No. Zarvenor is a non-custodial decision support platform. Your assets remain with your bank, stock exchange or depository. You receive analyzes and recommendations and decide for yourself about the implementation. There is no automatic disposal of your holdings.

Which data sources and latencies are underlying?

We process aggregated market data such as prices, volatility metrics, order book and liquidity metrics in near real time. Each output contains data status and timestamp. If the data quality is poor or the feeds are delayed, the system explicitly flags the limited significance.

What distinguishes signals from automated execution?

Signals are well-founded recommendations with triggers, confidence and risk classification. An automated execution would act without your approval. Zarvenor does not run automatically. You check the audit trail and implement recommendations in your existing setup.

For which portfolio sizes and B2B applications is the platform suitable?

The platform is aimed at capital-oriented private investors, family offices and B2B decision-makers, for example in the treasury or finance sectors, who want to systematically examine digital assets. The prerequisite is the willingness to use rule-based discipline and documented processes. A strategy discussion clarifies whether the profile and methodology fit together.

Further questions? Read detailed FAQ or Get in touch.

Request your strategy dossier

Get a structured introduction to methodology, risk rules and audit trails. We will contact you with a reliable overview and a suggestion for analysis access tailored to your investor profile.

  • ✓ Methodology document with backtest principles
  • ✓ Classification of drawdown thresholds and confidences
  • ✓ Non-binding, advice-oriented initial consultation

By submitting your request you agree to be contacted. Details can be found at Data protection. No passing on to third parties for advertising purposes.